Building a Money System: Financial Discipline for Men
Most men do not have a spending problem. They have a visibility problem, and visibility is not fixed by willpower, a New Year's resolution to "be better with money," or vague guilt every time a bank balance notification pops up. It is fixed by a system, a repeatable weekly structure that makes your financial position impossible to ignore and your decisions deliberate instead of reactive. Financial discipline built on willpower alone fails the same way every other willpower-only habit fails, inconsistently and usually right when you need it most. A system does not have that weakness.
Why Willpower-Based Budgeting Fails
The standard advice, track every expense, stick to strict category limits, review daily, assumes a level of sustained vigilance that few people, regardless of discipline, can maintain indefinitely. Psychologist Roy Baumeister's research on self-control found that willpower operates as a depletable resource, drawn down by every act of restraint across a day, which means a budgeting system that demands constant, moment-by-moment restraint is fighting against the same finite reserve that governs every other discipline in your life.
This is why so many men start a strict budget with real commitment and abandon it within a month, not from lack of genuine intent, but because a system requiring daily willpower against every purchase decision is structurally unsustainable. The fix is not more discipline. It is a system that requires discipline in fewer, more concentrated moments rather than continuously throughout every day.
The Weekly Money System
A fixed weekly money review, not daily tracking. Once a week, at a consistent time, review your accounts, your spending from the week behind, and your commitments for the week ahead. This single concentrated session replaces the unsustainable demand of constant daily vigilance with one deliberate, manageable checkpoint, doing far more for your actual financial awareness than sporadic, anxious daily glances at your balance ever could.
Automate what you can, so willpower is not required for it. Automatic transfers to savings, automatic bill payments, automatic investment contributions, set up once and then removed entirely from the list of daily decisions. This is the single highest-leverage move in building financial discipline, because a decision made once, structurally, does not require repeated willpower the way a manual monthly transfer does, competing against a hundred other spending temptations every single time.
Set three financial goals, not fifteen. The same discipline that applies to broader goal setting applies directly here. A vague, sprawling list of financial ambitions, an emergency fund, a house deposit, debt payoff, an investment target, a vacation fund, all pursued simultaneously with no clear priority, tends to produce slow progress on all of them rather than real momentum on any. Rank your three highest-priority financial goals and direct your available surplus toward those specifically, adjusting the rest of your ambitions to wait their turn.
Build a spending plan, not just a restriction list. A budget framed entirely around restriction, what you cannot buy, tends to trigger the same rebound effect that plagues any suppression-based behavior change. A spending plan that deliberately allocates money toward things you genuinely value, alongside your savings and debt goals, tends to hold up better over time than a purely restrictive budget that treats every discretionary purchase as a moral failure.
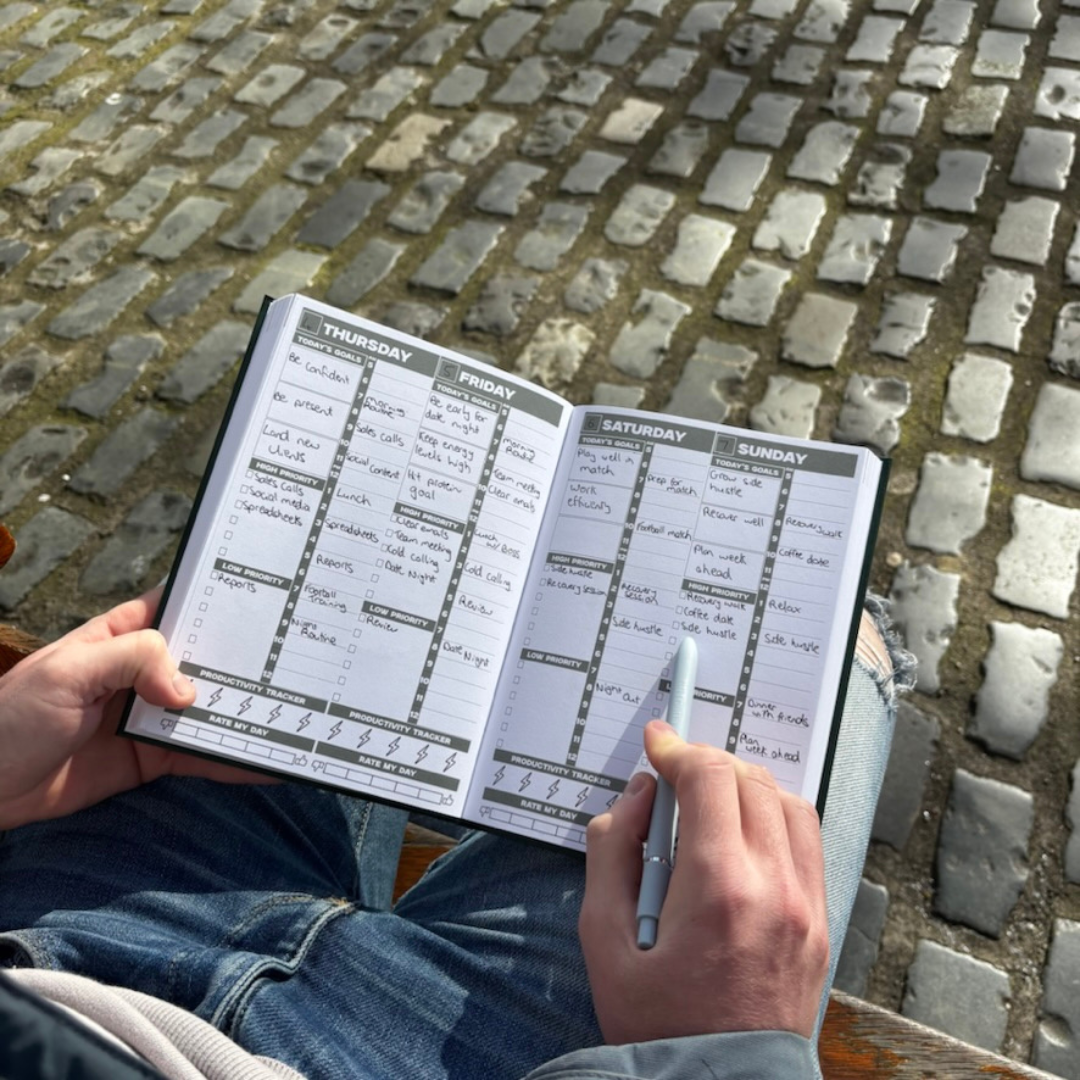
The Plan Your Growth undated weekly agenda includes space for exactly this kind of weekly review and goal tracking, so your financial system sits alongside the rest of your weekly planning rather than existing in a separate app you only open when anxiety finally forces you to look.
Why the Weekly Review Beats Daily Tracking
There is a common assumption that more frequent tracking produces better financial outcomes, but the evidence points toward consistency of review mattering more than frequency. A weekly review done reliably, every single week without fail, produces a far more accurate and actionable picture over time than daily tracking attempted with enthusiasm for two weeks and then abandoned entirely once life gets busy.
This mirrors the broader pattern seen throughout habit and behavior research: a sustainable, moderate practice consistently maintained outperforms an intense, demanding practice abandoned after a short burst of initial motivation. The weekly money date is deliberately sized to be sustainable indefinitely, thirty minutes, once a week, rather than a daily commitment that competes against a hundred other daily priorities and predictably loses.
Handling Irregular Income or Debt
For men with variable income, commission-based work, freelancing, seasonal fluctuation, the weekly system adapts naturally where a rigid monthly budget often does not. Instead of comparing this month to a fixed target that assumes consistent income, the weekly review tracks your actual trailing pattern, building a realistic baseline from your lower-earning periods and treating anything above that baseline as deliberately allocated surplus, directed toward your three priority goals rather than absorbed invisibly into daily spending.
For men working through debt, the weekly review is where the debt payoff plan gets concrete traction, tracking the specific number moving down week over week rather than an abstract annual goal that offers no near-term feedback. Seeing the number move, even slowly, provides the kind of regular positive feedback that sustains motivation far better than a distant, single annual checkpoint.
Building Financial Confidence, Not Just Financial Control
A weekly money system does more than control spending. Over months, it builds a genuine, evidence-based confidence in your financial position, replacing the vague, anxious uncertainty that comes from avoidance with an actual, current picture of where you stand. This confidence compounds its own value, since financial decisions made from a position of clear knowledge tend to be better decisions than ones made reactively, under stress, without a real sense of your actual numbers.
This is the deeper argument for building the system in the first place. It is not really about restriction. It is about replacing anxious uncertainty with structural clarity, so financial decisions become deliberate choices made with real information, rather than reactive guesses made under the discomfort of not actually knowing where things stand.
The Bottom Line
Financial discipline is not a personality trait some men have and others lack. It is a weekly system: a fixed review session, automated transfers that remove daily willpower from the equation, three prioritized goals instead of fifteen scattered ones, and a spending plan that allocates rather than only restricts. Willpower-based budgeting fails because it demands constant vigilance from a finite resource. A weekly system succeeds because it concentrates the discipline into one deliberate session and automates the rest.
The Plan Your Growth undated weekly agenda gives your weekly money review a real, recurring home alongside the rest of your planning, so financial discipline becomes one more tracked habit in a system you already trust, rather than a separate anxiety you only address when it becomes unavoidable.