Financial Goal Setting for Men Tired of Vague Money Plans
"Save more" and "get better with money" are not goals. They are wishes wearing the language of a goal, and wishes do not produce compound interest. Financial goal setting that actually moves the needle requires the same specificity as any other serious execution system: a defined number, a defined timeline, and weekly actions that ladder up to it directly. Most men who feel like they are "bad with money" are not undisciplined, they simply never converted a vague financial wish into an executable system, and the gap between those two things is where most financial progress quietly dies.
Why Most Men Avoid This Level of Specificity
There is a reason vague financial goals persist despite everyone knowing, at some level, that they do not work. Specificity forces confrontation with the actual gap between where you are and where you want to be, and that confrontation is uncomfortable in a way that a vague aspiration is not. "Save more" allows you to feel like you are working toward something without ever measuring whether you actually are. Financial goal setting done properly removes this comfortable ambiguity, which is exactly why it works and exactly why it takes deliberate effort to commit to, rather than something that happens naturally without a decision to do it differently.
Why Vague Financial Goals Never Materialise
"Save more this year" has no clear finish line, no defined action, and no way to measure whether this month's progress is on track or badly behind. This vagueness is not a minor flaw, it is disqualifying. A brain cannot execute against an undefined target the same way it cannot plan a route to an undefined destination. Financial goal setting has to start by converting every vague money wish into a specific number with a specific deadline: not "save more" but "€10,000 in an emergency fund by December 31," not "pay down debt" but "clear the €4,000 credit card balance in six months."
This specificity does something practical beyond sounding more serious. It makes the goal measurable weekly, which means progress or lack of it becomes visible immediately rather than only becoming obvious in a painful year-end review.
Breaking the Number Into Weekly Execution
Once the target number and deadline exist, the next step is dividing it into a weekly or monthly action, the actual mechanism that gets executed regardless of motivation. A €10,000 emergency fund in twelve months is €192 a week, a specific, schedulable, trackable amount rather than an abstract yearly target that provides no weekly signal about whether you are on pace.
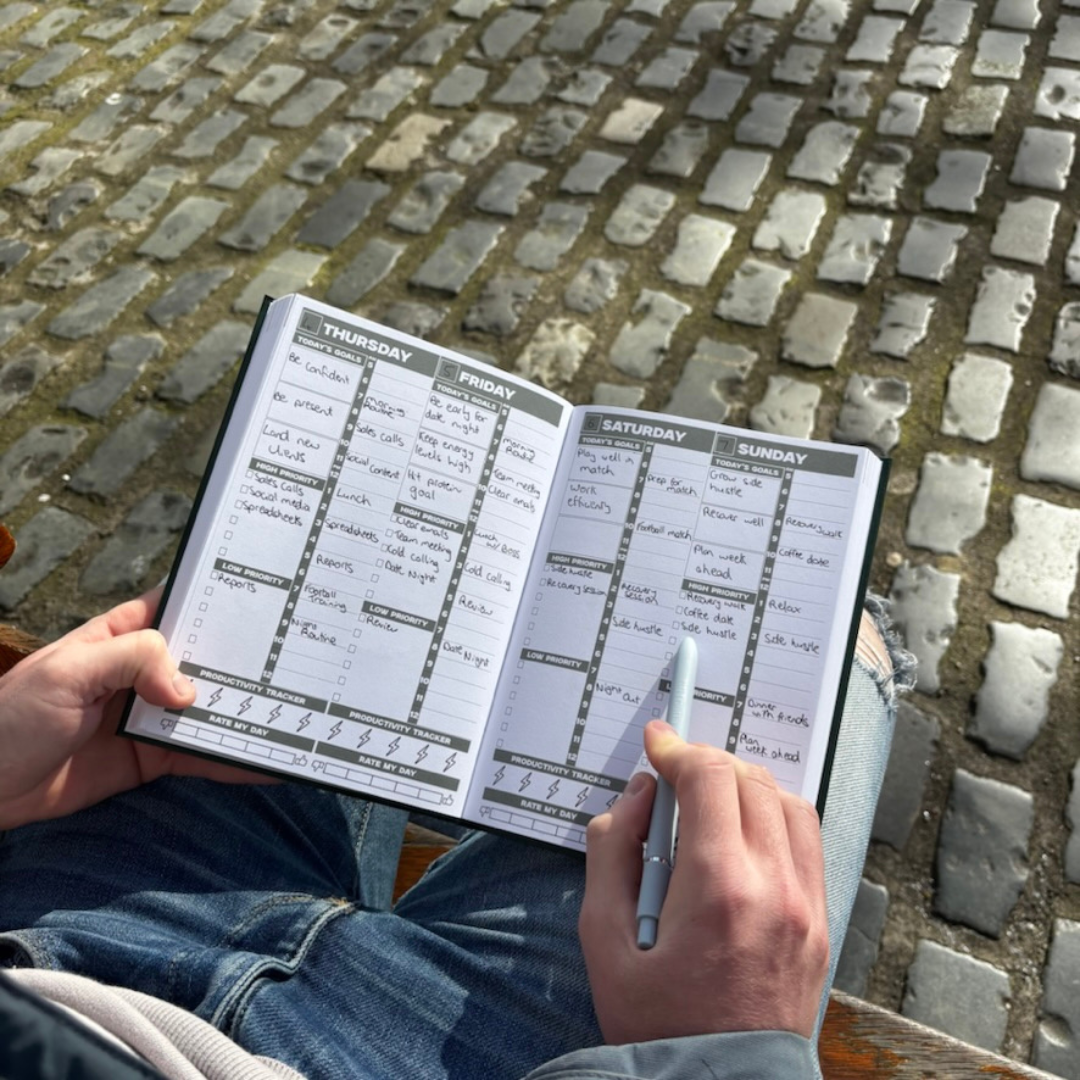
This weekly breakdown is where financial goal setting becomes an execution problem rather than a wishing problem, and it belongs in the same system that holds every other weekly commitment. Inside the Plan Your Growth undated weekly agenda, a weekly financial check-in sits alongside work and fitness targets, treating the money goal with the same structural seriousness as everything else that gets tracked weekly rather than leaving it to a once-a-year resolution that never gets revisited.
Automating the Weekly Number Wherever Possible
Once the weekly contribution amount is defined, automating it, a standing transfer that executes without requiring a fresh decision each week, removes the single largest point of failure in most financial goal setting: the moment of choice each week where a competing expense makes the contribution feel optional. An automated transfer treats the financial goal the same way a scheduled bill gets treated, as a fixed, non-negotiable line item rather than a discretionary choice re-litigated weekly. Men who automate this step consistently outperform men relying on manual weekly transfers, not because of superior discipline, but because the automated version removes the decision entirely rather than requiring it to be won repeatedly.
The Weekly Money Review
A five-minute weekly check, the same day as your broader weekly review, keeps financial goal setting connected to actual behaviour instead of drifting into an annual abstraction. Three questions: did this week's specific action happen (the transfer, the extra payment), is the pace still on track for the deadline, and is anything about next week's spending going to threaten the target. This is not a full accounting exercise, it is a quick pulse check that catches drift within a week instead of within a quarter, when it is far harder to recover the lost ground.
Adjusting for Variable Income
Men with commission-based or variable income face a specific complication in financial goal setting: a fixed weekly contribution amount does not fit cleanly against income that fluctuates month to month. The fix is planning from a conservative baseline, using your lowest realistic month as the figure the weekly contribution is calculated against, rather than an average that assumes every month performs like the good ones. Any income above that baseline becomes an accelerator, an opportunity to get ahead of the twelve-month target rather than a buffer quietly absorbed into lifestyle spending without ever reaching the goal at all.
Prioritising Which Goal Comes First
Most men trying to improve their finances attempt multiple goals simultaneously: paying down debt, building savings, and investing, all at once, with resources split thin across all three and meaningful progress on none of them. Financial goal setting works better with a strict priority order, executed sequentially rather than in parallel wherever possible. High-interest debt first, because the interest cost typically exceeds any reasonable investment return. Then an emergency fund, because without one, any unexpected cost becomes new debt, undoing progress already made. Only then does investing or larger wealth-building goals take the primary focus.
This sequencing is not about ignoring the other priorities entirely, it is about directing the bulk of deliberate effort toward the highest-leverage target first, rather than spreading resources so thin across three goals that none of them move meaningfully within the year.
Reviewing the Goal Every Quarter, Not Just at the Deadline
A twelve-month financial target benefits from a check-in more frequent than the final deadline alone. A quarterly review, comparing actual progress against the pace required to hit the target on time, catches drift early enough to correct it, a slightly higher weekly contribution for the remaining months, rather than discovering at month eleven that the pace was never going to reach the goal and there is no longer enough runway left to fix it.
Handling the Month Something Goes Wrong
Every financial plan eventually meets an unplanned cost, a car repair, a medical bill, something that eats into the week's planned contribution. The mistake is treating this as proof the whole system has failed and abandoning the target altogether. The correct response is the same triage used in any execution system: assess the actual damage to the timeline, adjust the weekly number slightly if needed to still hit the deadline, and continue. A single disrupted week rarely threatens a twelve-month target if it gets absorbed immediately rather than becoming the excuse for a months-long abandonment of the entire goal.
The Bottom Line
Financial goal setting only works when a vague money wish gets converted into a specific number, a specific deadline, and a weekly action that ladders up to it directly. Track it with a five-minute weekly review, prioritise sequentially rather than splitting focus across every goal simultaneously, and treat a disrupted week as a minor adjustment rather than a reason to quit. The gap between men who talk about improving their finances and men who actually do is almost always this specificity, not raw discipline.
Build your weekly financial check-in into the Plan Your Growth undated weekly agenda, and give the goal the same weekly accountability as everything else you are actually serious about.